
Why Your First Financial Goal Should Not Be Rs 10 Lakh
Why Your First Financial Goal Should Not Be Rs 10 Lakh
For most young professionals in India, the first serious financial goal is a round number. Ten lakh rupees in an investment corpus is the version most people settle on.
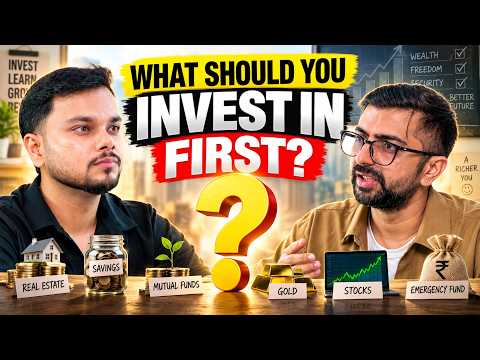
Neeraj Arora, speaking on Accompany Akki, argues that chasing this number before covering basic risk is a mistake that can undo years of saving in a single bad event.
The order most people get wrong
Neeraj's argument starts with a simple question: do you have medical insurance? Do you have term insurance?
For most youngsters focused on building an investment corpus, the honest answer is no. He treats this as a serious gap, not a minor oversight.
The math behind his concern is straightforward. A medical emergency in the family can generate a hospital bill of five to six lakh rupees.
If that bill has to come out of a hard-earned investment corpus, more than half of it can disappear in one event. Term insurance covers a related but different risk, protecting dependents if the primary earner is no longer around.
His recommended order is: medical insurance first, term insurance second, an emergency fund third, and only then a SIP into index funds such as Nifty 50 and Nifty Next 50.
He notes that the emergency fund does not need to be completed before investing starts. It can be built in parallel, with monthly surplus split between the two.
Why simple advice gets ignored
Neeraj is candid about why so many people skip this sequence even when they know it makes sense.
Index fund investing is boring. It does not produce a story worth telling. So instead, people chase small caps, mid caps, or complex products that sound impressive when explained to others.
He describes this as investing to show off rather than investing toward a goal, and argues that the two rarely lead to the same outcome.
Goal based investing tends to be quiet and unremarkable in the moment, visible only in results achieved over time.
Show-off investing, driven by ego and the desire for novelty, tends to work against the investor's own long term interests.
A deliberately narrow playbook
For anyone starting out, especially those earning between Rs 50,000 and Rs 1 lakh a month, Neeraj's suggestion is short: term insurance, medical insurance, an emergency fund, and index funds.
He calls this more than sufficient. Once someone has two to three years of index fund exposure, a small allocation to gold or international markets can be considered, though he is clear this step is optional.
The underlying message is that behavior matters more than product selection.
Neeraj teaches mutual funds professionally, but he considers correcting investor behavior his real job, since even a well chosen fund cannot save an investor from poor decision making driven by impatience or ego.
For young professionals confused about where to start with money, the takeaway from this conversation is that the first move has nothing to do with picking an investment.
It starts with protecting against the risks that could erase everything else.
Full podcast-
More from the blog

Subscribe to our newsletter
The best new roles, resources and must-watch episodes — in your inbox every week. No spam, unsubscribe anytime.
