
Term Insurance Is Not An Investment: Neeraj Arora Explains Why
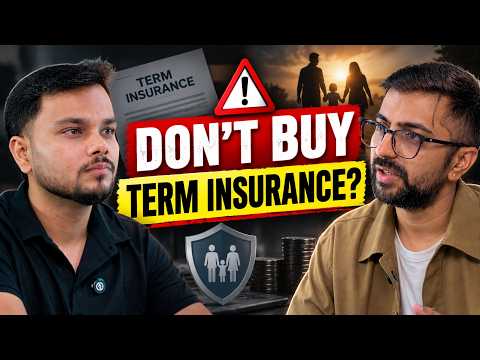
Stop Expecting Returns From Your Term Insurance
There is a specific financial mistake that quietly costs Indian families more than almost any other, and it isn't a bad stock pick or a missed SIP.
It's the decision to skip term insurance, or worse, to buy it while secretly expecting it to behave like an investment.
Neeraj Arora addressed this head-on in a recent conversation on Accompany Akki, and his framing is worth sitting with because it cuts through a debate that trips up most people in their 20s and 30s.
The core confusion
Term insurance, Neeraj explains, exists for exactly one purpose: to cover risk.
If something happens to you, the people who financially depend on you receive support. That's the entire product.
It was never designed to build wealth, generate returns, or double as a savings instrument.
The confusion arises because Indians are trained to ask "what do I get back" from every financial product.
We do it with cars, we do it with gadgets, and we do it with insurance too.
Neeraj's counter to this is a simple analogy: you don't buy a BMW and ask about its mileage.
You buy it for what it does, not for a return on investment. Term insurance deserves the same clarity.
Who should actually buy it
Not everyone needs term insurance, and Neeraj is upfront about the two situations where it makes no sense.
First, if you have no financial dependents and have no plans to create any, there's simply nobody who needs the payout.
Buying a policy in that situation is money spent for no functional reason.
Second, and this is a more advanced case, if your portfolio has grown large enough that your family could survive comfortably without the insurance payout, you no longer need the policy either.
Neeraj places himself in this category today. His portfolio has reached a size where the term insurance payout would be a small fraction of his overall net worth.
But he still holds the policy, because of a decision he made two decades earlier.
Buy early, because the math only gets worse
The single biggest piece of advice in the conversation is about timing.
Neeraj describes a pattern he has seen repeatedly: people in their mid-20s skip term insurance because they'd rather put that money into mutual funds.
At that age, without dependents, that reasoning is often rational.
But the same people, once they hit their early thirties and start having dependents, suddenly need coverage and discover premiums have jumped considerably, often crossing 35,000 to 40,000 rupees annually for a policy that would have cost far less a few years earlier.
His own story runs counter to that pattern. At 24-25, while teaching income tax to students and going through sections 80C and 80D of the Income Tax Act, he came across the concept of term insurance and decided to take a policy immediately.
He started with 60 lakhs of coverage and later added a top up of 1.5 crore as his financial responsibilities grew.
A rule of thumb for coverage amount
Beyond timing, Neeraj offers a concrete number to work with.
Your term insurance cover should be at least 20 times your yearly income.
The logic is that this roughly replaces two decades of your earning potential for your dependents, giving them a realistic runway to adjust financially if you are no longer around.
The security guard analogy
One of the more memorable moments in the conversation is when Neeraj compares term insurance to a security guard outside a residential building.
You respect the guard, you value the protection they provide, but you would never expect them to go fight a war at the border.
That's the army's job, not theirs. In the same way, you buy term insurance for the specific job of covering risk, and you don't expect it to also perform the job of an investment product.
Why mis-selling happens
Perhaps the most pointed observation Neeraj makes is about why insurance mis-selling is so widespread in India.
His view is that mis-selling doesn't happen in a vacuum. It happens when the buyer is also a little greedy, wanting both protection and guaranteed returns from a single product. Agents sell that fantasy because there is a market willing to buy it.
The products that promise both insurance and investment returns often end up doing neither particularly well, but they sell because they cater to a desire people already have.
His solution is simple in principle, even if it requires discipline in practice: keep insurance and investment completely separate. Buy term insurance purely for risk cover, and put your investment money into instruments actually designed for growth, like mutual funds or equities.
A generational blind spot
Neeraj also touches on why an older generation largely skipped term insurance altogether.
Their reasoning was that the money simply disappears if nothing happens to you, so why pay for it.
That mindset, according to him, comes from the same instinct that makes people evaluate every purchase purely by what they get back, missing the point of products designed for protection rather than return.
This generational gap partly explains why so many young professionals today still hesitate over term insurance, even when they can clearly articulate why they need health insurance.
The habit of separating "protection products" from "return-generating products" simply hasn't been passed down as clearly.
The bottom line
Term insurance is not there to make you money. It exists so that the people who depend on you financially don't lose everything if you are no longer around to provide for them.
Buy it for that reason and that reason alone. If you have dependents, don't wait. Buy it early, buy enough of it, roughly 20 times your annual income as a benchmark, and stop expecting it to behave like an investment.
That single mental shift, according to Neeraj Arora, is what separates people who are actually protected from people who think they are.
Watch the full conversation with Neeraj Arora-
More from the blog

Subscribe to our newsletter
The best new roles, resources and must-watch episodes — in your inbox every week. No spam, unsubscribe anytime.
